
Nigeria’s economic story is shifting from one of squandered oil riches to a difficult but potentially transformative reform era, according to Independent Media and Policy Initiative (IMPI).
In its Policy Statement 046, signed by Chairman Dr Omoniyi Akinsiju, the policy group compared two sharply different periods of economic management: the commodity-driven years from 1999 to 2015 and the structural reforms launched in 2015 and accelerated from 2023 to 2026.
IMPI said Nigeria’s oil boom between 2000 and 2014 generated enormous external surpluses. The country’s current-account surplus exceeded $29 billion in 2008, while foreign reserves climbed to a record $62 billion.
But the windfall, the group argued, was not converted into lasting industrial capacity or a diversified economy. Instead, much of the money went toward consumption, debt repayment—including $12 billion paid to Paris Club creditors—and recurrent government spending.
IMPI also criticised the management of the Excess Crude Account, which it described as lacking constitutional backing. The account reportedly fell from $22 billion in 2008 to less than $3 billion by 2014 after state-level distributions drained its resources.
At the same time, the Central Bank of Nigeria used foreign-exchange earnings to support the naira, subsidise imports and finance imported refined petrol, while domestic refineries remained largely inactive, IMPI said.
When oil prices collapsed in late 2014, the weaknesses became impossible to conceal. Nigeria entered a severe currency crisis and suffered its first major recession in decades by 2016. Poverty rates rose sharply, reaching between 45 and 53 percent, according to the statement.
The vulnerabilities persisted. Nigeria recorded consecutive current-account deficits, with the shortfall reaching $17 billion in 2019 and $15.8 billion in 2020.
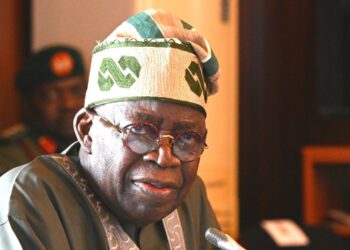
IMPI said the turning point came with the market reforms introduced under President Bola Ahmed Tinubu from 2023, particularly the unification of foreign-exchange markets and the removal of petrol subsidies.
The changes triggered painful consequences, including higher inflation and a steep naira depreciation. But IMPI argued that they also began repairing the country’s external accounts, helping Nigeria move from recurring deficits to a sustained run of current-account and merchandise-trade surpluses.
Gross foreign reserves, the group said, rose from $45 billion to $55 billion by the third quarter of 2026—equivalent to more than 14 months of import cover.
The statement further credited expanding domestic refining capacity with helping Nigeria move from dependence on imported fuel to exporting refined petroleum products across West Africa.
Non-oil exports, including agricultural goods, solid minerals and industrial chemicals, have also grown significantly, it said.
IMPI added that improved economic credibility has been reflected in more favourable assessments from Moody’s, Standard & Poor’s and Fitch, while stronger investor confidence has contributed to gains on the Nigerian Exchange.
The central message of the report is clear: Nigeria’s first oil boom created wealth without resilience; the current reform era, though costly, is intended to build an economy that can withstand shocks and grow through production rather than consumption.