Nigeria’s economic recovery is gaining traction, but the country’s reform
programme faces a crucial test as the 2027 elections approach.
The World Bank says stronger growth, easing inflation and improved investor confidence are creating the foundations for a more stable economy.
It warns, however, that rising pre-election spending could weaken fiscal discipline, slow reforms and erode the public support needed to sustain Nigeria’s difficult macroeconomic adjustment.
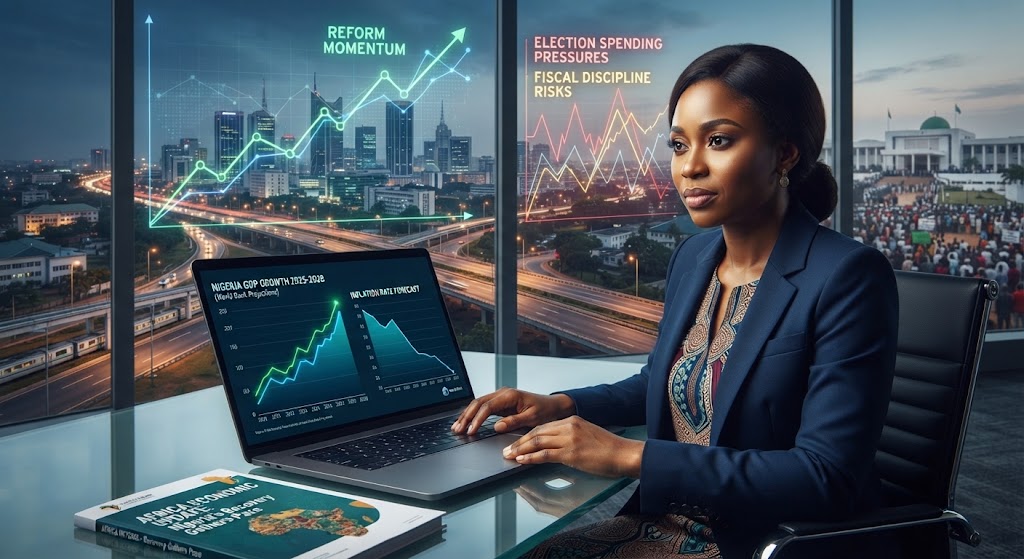
In its Africa Economic Update: October 2026, the World Bank projects Nigeria’s economic growth will rise from 4.0 percent in 2025 to 4.3 percent in 2026, before reaching 4.4 percent annually in 2027 and 2028.
The outlook places Nigeria among the major economies in Sub-Saharan Africa whose growth projections were upgraded after strongerthan-expected activity.
The improvement is being driven mainly by the services sector, particularly financial services, information and communications technology, and real estate. These industries have benefited from continuing digitalisation and resilient domestic demand.
The World Bank also expects agriculture to recover in 2026, although it projects more moderate momentum in industry as oil production and manufacturing lose some speed.
Recent data point to a broadening recovery. Nigeria’s economy grew 4.43 percent yearon-year in the second quarter of 2026, up from 4.23 percent in the same quarter of 2025.
Agricultural growth accelerated to 4.39 percent, compared with 2.82 percent a year earlier, while services expanded by 4.6 percent.
The oil sector also rebounded, with real oil GDP rising 7.3 percent year-on-year in the second quarter.
Its contribution to overall growth, however, remained modest at 0.2 percentage point, reinforcing the importance of non-oil activity to Nigeria’s recovery.
Industrial growth moderated to 4.0 percent, from 7.5 percent in the same quarter of 2025, revealing that the recovery remains uneven across sectors.
Business activity showed further signs of strength in August. The Stanbic IBTC Purchasing Managers’ Index increased to 54.3, from 52.5 in July, as new orders and customer demand improved.
Firms accelerated production across several sectors, particularly agriculture and manufacturing, and employment expanded for a 15th consecutive month.
Yet hiring remained modest compared with the pace of business activity, suggesting that economic growth is not yet generating jobs at the scale required by Nigeria’s rapidly expanding labour force.
Inflation is easing, but fiscal pressures remain
The World Bank expects inflation to fall from 23.0 percent in 2025 to 15.7 percent in 2026, and to 12.2 percent by 2028.
Monetary tightening, exchange-rate stabilisation and improved supply conditions are expected to support the decline.
That disinflation would provide much-needed relief to households, restore some purchasing power and help reduce poverty gradually. But the World Bank cautions that the pace of poverty reduction will remain limited.
Elevated fuel prices linked to the conflict in the Middle East are weighing disproportionately on low-income households, while higher food, transport and energy costs continue to threaten household welfare.
The fiscal challenge is to protect vulnerable Nigerians without undoing the reforms designed to restore macroeconomic stability.
Nigeria has largely maintained market-based fuel pricing, avoiding the large and recurring cost of broad fuel subsidies.
The World Bank says preserving those pricing reforms is important, but adds that targeted support may be necessary to cushion poor households from the effects of higher energy costs.
That balance will become more difficult if political pressures intensify before the 2027 elections.
Election-year spending can increase demands for public-sector wages, infrastructure projects, transfers and subsidies, while weakening efforts to contain deficits and improve the quality of public expenditure.
If spending rises without corresponding
gains in revenue and productivity, it could renew inflationary pressure, increase borrowing needs and place further strain on already limited fiscal space.
The World Bank specifically identifies rising pre-election spending ahead of the 2027 elections as a downside risk to Nigeria’s outlook.
It warns that excessive spending could
weaken reform momentum and erode the social consensus needed to sustain the country’s ongoing macroeconomic adjustment.
External accounts are improving—but remain exposed
Nigeria’s external position is expected to strengthen in the near term. The current -account surplus is projected to widen from 4.8 percent of GDP in 2025 to 6.0 percent in 2026, supported partly by higher oil prices and stronger export earnings.
The surplus is then expected to narrow to 3.4 percent of GDP by 2028, as oil prices normalise and import demand increases.
The improvement provides some breathing room for the government and the central bank. But it also highlights Nigeria’s continued exposure to oil-price volatility.
Higher oil prices can strengthen fiscal and external accounts, yet they can simultaneously raise domestic fuel and transport costs.
The resulting gains may therefore be partly offset by inflation, weaker household purchasing power and greater pressure on social protection.
The World Bank also warns that increased global uncertainty could trigger capital-flow volatility.
Tighter global financial conditions would raise the cost of borrowing and could place additional pressure on the naira, reserves and debt-service obligations.
For policymakers, maintaining investor confidence will require consistent fiscal management and continued progress on exchange-rate and monetary reforms.
Energy reforms offer a buffer
Nigeria is better placed than many Sub-Saharan African economies to absorb a global energy shock because it is a net oil exporter.
Higher oil prices can increase export earnings and government revenues. The country’s resilience is also supported by expanded domestic refining capacity and the Compressed Natural Gas initiative.
Domestic refining could reduce Nigeria’s dependence on imported petroleum products, while the wider use of compressed natural gas could offer consumers a cheaper alternative to petrol and strengthen long-term energy security.
The World Bank describes these
measures as important country-specific buffers. But the report stresses that energy advantages will not automatically produce broad economic resilience.
Their impact will depend on the quality of fiscal and exchange-rate management and on whether additional revenues reach households and businesses through public spending, productive investment and targeted social support.
The government therefore faces a delicate choice. It must preserve market-based energy reforms to protect public finances, while ensuring that the immediate burden of higher fuel prices does not deepen poverty or undermine support for reform.
Poorly targeted electionyear relief could recreate the fiscal problems that the reforms were intended to resolve;
insufficient support could intensify social resistance.
Growth must translate into jobs and living standards
Nigeria’s improving growth figures are encouraging, but the World Bank’s wider regional assessment offers an important warning: growth alone may not deliver significant poverty reduction.
Across Sub-Saharan Africa, economic expansion has often been concentrated in capital-intensive sectors with weak links to employment and household incomes. Rapid population growth has also diluted gains in per-capita income.
Nigeria faces the same risk. A recovery led by finance, ICT, real estate and oil can strengthen headline GDP without generating enough decent jobs for young people or substantially improving conditions for poor households.
The expansion of Nigeria’s digital economy offers a promising route to productivity and employment, but access to technology remains uneven and the country’s digital talent base is still small relative to those of Asia and Europe.
The challenge for the government is to use the current recovery to expand productive investment, improve electricity and transport infrastructure, deepen financial inclusion and strengthen agriculture and manufacturing.
Those priorities require fiscal resources—but they also require spending discipline, transparent budget execution and protection from politically motivated projects with limited economic returns.
The 2027 choice
Nigeria enters the election cycle with a more favourable economic outlook than it had during the worst phase of its inflation and exchange-rate pressures.
Growth is accelerating, business activity is strengthening, agriculture is recovering and inflation is projected to decline. The current-account position is improving, while refining and CNG initiatives offer
additional energy buffers.
Yet the recovery remains vulnerable. A renewed Middle East conflict, tighter global financial conditions, insecurity, climate-related shocks or disruptions to oil production could quickly weaken the outlook.
Pre-election spending could magnify those pressures if it undermines fiscal consolidation, fuels inflation or diverts funds from productive investment and targeted social protection.
The World Bank’s warning is not that election spending will inevitably derail Nigeria’s reforms. It is that the approach to spending in the run-up to 2027 will help determine whether the recovery becomes durable or temporary.
The test is therefore broader than the next growth figure. Nigeria must show that it can preserve macroeconomic stability while protecting vulnerable households, maintain reform momentum during a politically sensitive period and convert stronger growth into jobs, lower living costs and better public services.
If it succeeds, the 2027 election cycle could consolidate the country’s recovery. If fiscal discipline gives way to short-term political pressures, Nigeria could find that the gains of reform are once again overwhelmed by inflation, debt and weakened investor confidence.